


U.S. poultry products hold leading positions in both international and U.S. meat commodity markets—supported by competitive production structures, modern poultry genetics, abundant domestic feed resources, and strong consumer appeal. In 2025, total poultry sector sales were $81.7 billion, up from $70.3 billion in 2024. Broilers accounted for 54.6 percent of poultry sector value in 2025, with $44.6 billion. This value was a decrease of 1.8 percent from 2024. Benchmark broiler prices were down about 5 cents year over year in 2025. The value of turkey production bounced back from $3.7 billion in 2024 to $5.6 billion in 2025. Average wholesale prices for whole-hen turkeys in 2025 were up 42 cents from the year before. The value of egg production in 2025 was $31.5 billion, up $10.3 billion from 2024. The annual average wholesale prices for table eggs climbed in both 2024 and 2025.
Production
U.S. broiler production has consistently expanded since 2013, as producers sought to meet domestic and foreign consumer demand. Production of turkey meat and table eggs have shown year-over-year declines in recent years. From 2015 to 2025, broiler production expanded by 19.9 percent. In the same period, turkey production declined by 13.9 percent and table-egg production increased by 6.9 percent.
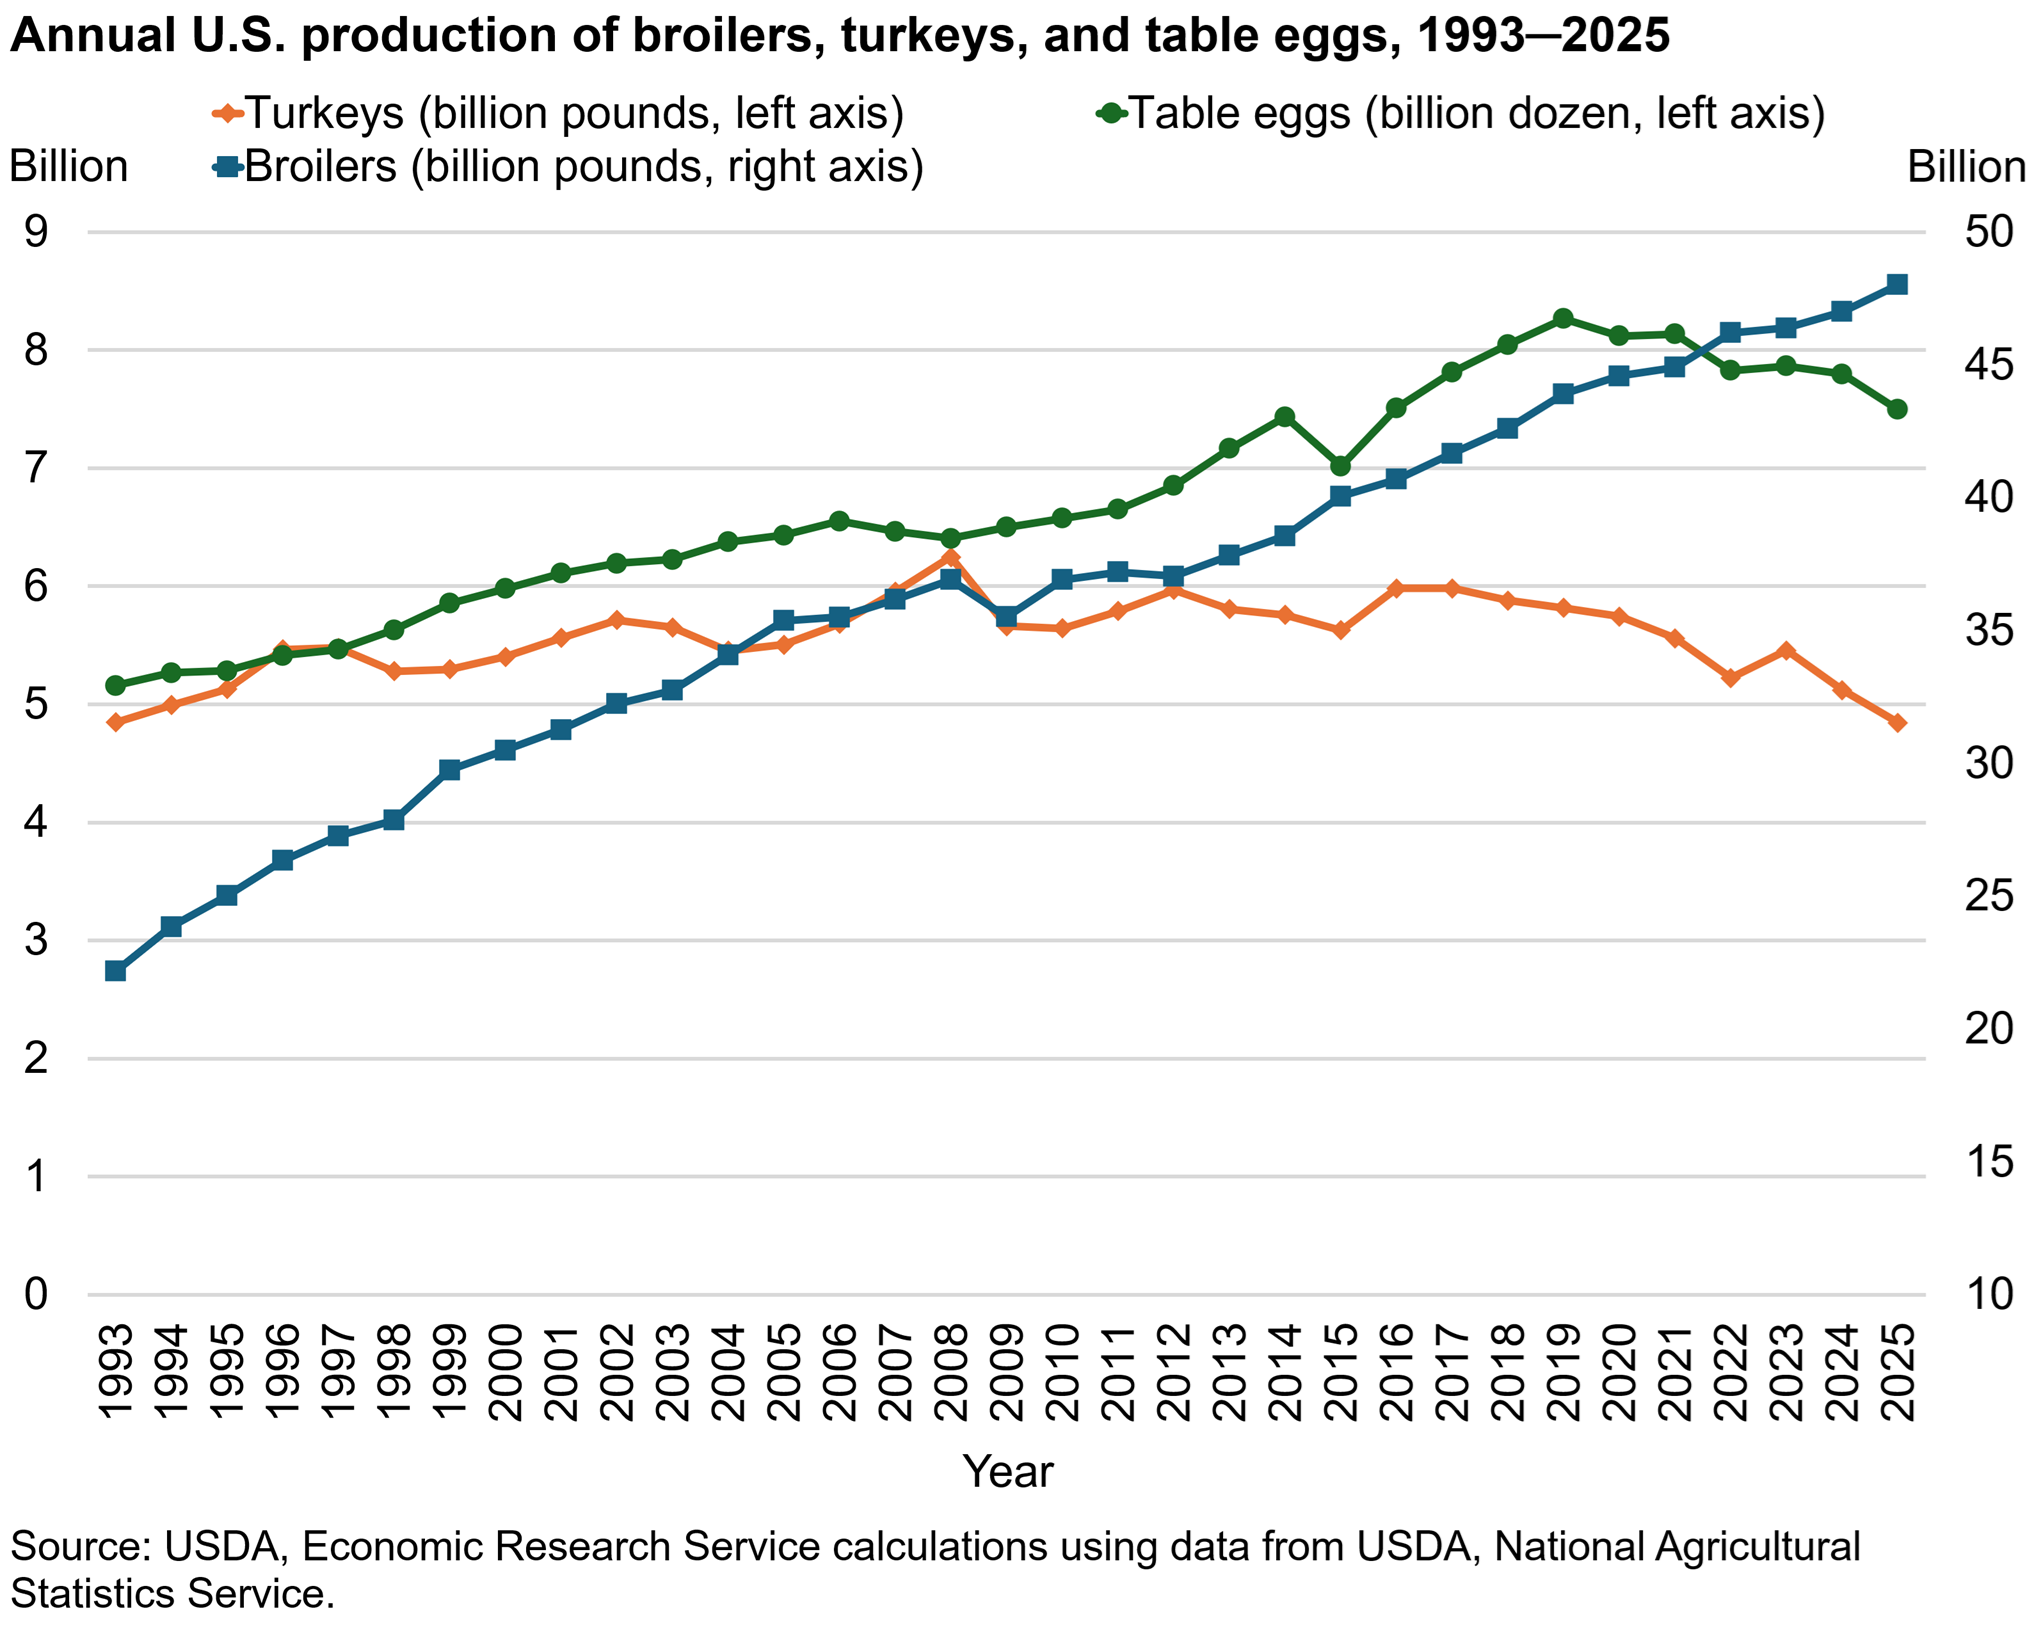
Download chart image | Chart data
U.S. poultry production has a competitive global advantage due to abundant domestic feed resources, primarily soybean meal and corn. Feed is generally the most significant production cost across livestock, and poultry converts feed to human food products (meat and eggs) more efficiently than larger livestock. Modern poultry genetics have driven a dramatic increase in poultry-feed conversion over time, requiring less feed (and duration) to produce market-ready birds (and eggs) and resulting in highly competitive product prices.
Commercial poultry production starts with primary breeder birds selected to lay fertile eggs for hatching on the basis of desirable genetic traits. These birds’ progeny become breeders that eventually produce birds used directly for meat or table-egg production. The period during which breeder birds grow to reach reproductive maturity can be 4.5 to 6 months after hatching and is generally longer for turkeys.
Timeframes vary for harvesting meat from broilers or turkeys and table eggs from layer chickens. Market-broiler chickens are generally slaughtered before they reach 2 months of age, while turkeys often reach 4 months before slaughter. Table-egg-type chickens begin laying at about 4 to 4.5 months of age and start a cycle that can last 14–15 months, with additional production cycles optional after a molting period.
U.S. poultry firms vertically integrate more production stages than other livestock producers—with feed production, fertile egg and chick production, and slaughter often residing under the same firm. Production contracts are also common, where the services of growers who house and manage birds, for example, may be contracted by an integrated poultry firm in exchange for a fee per bird.
Consumption
U.S. poultry-meat consumption has trended up and displaced some red-meat consumption in recent decades, in part because of favorable prices and health recommendations. The chart below shows these changing consumption trends by comparing one measure of poultry-meat consumption (estimated retail disappearance) with the same measure for red-meat consumption, including beef and pork. The chart also includes egg and egg-product disappearance. USDA, Economic Research Service-published disappearance statistics are a proxy for consumption, measuring supplies available for marketing in a given period. Meat disappearance is equal to production less net exports and net changes in cold storage. Retail disappearance also subtracts an estimate of meat components that are not typically sold with meat at retail, such as certain bone portions and skin.
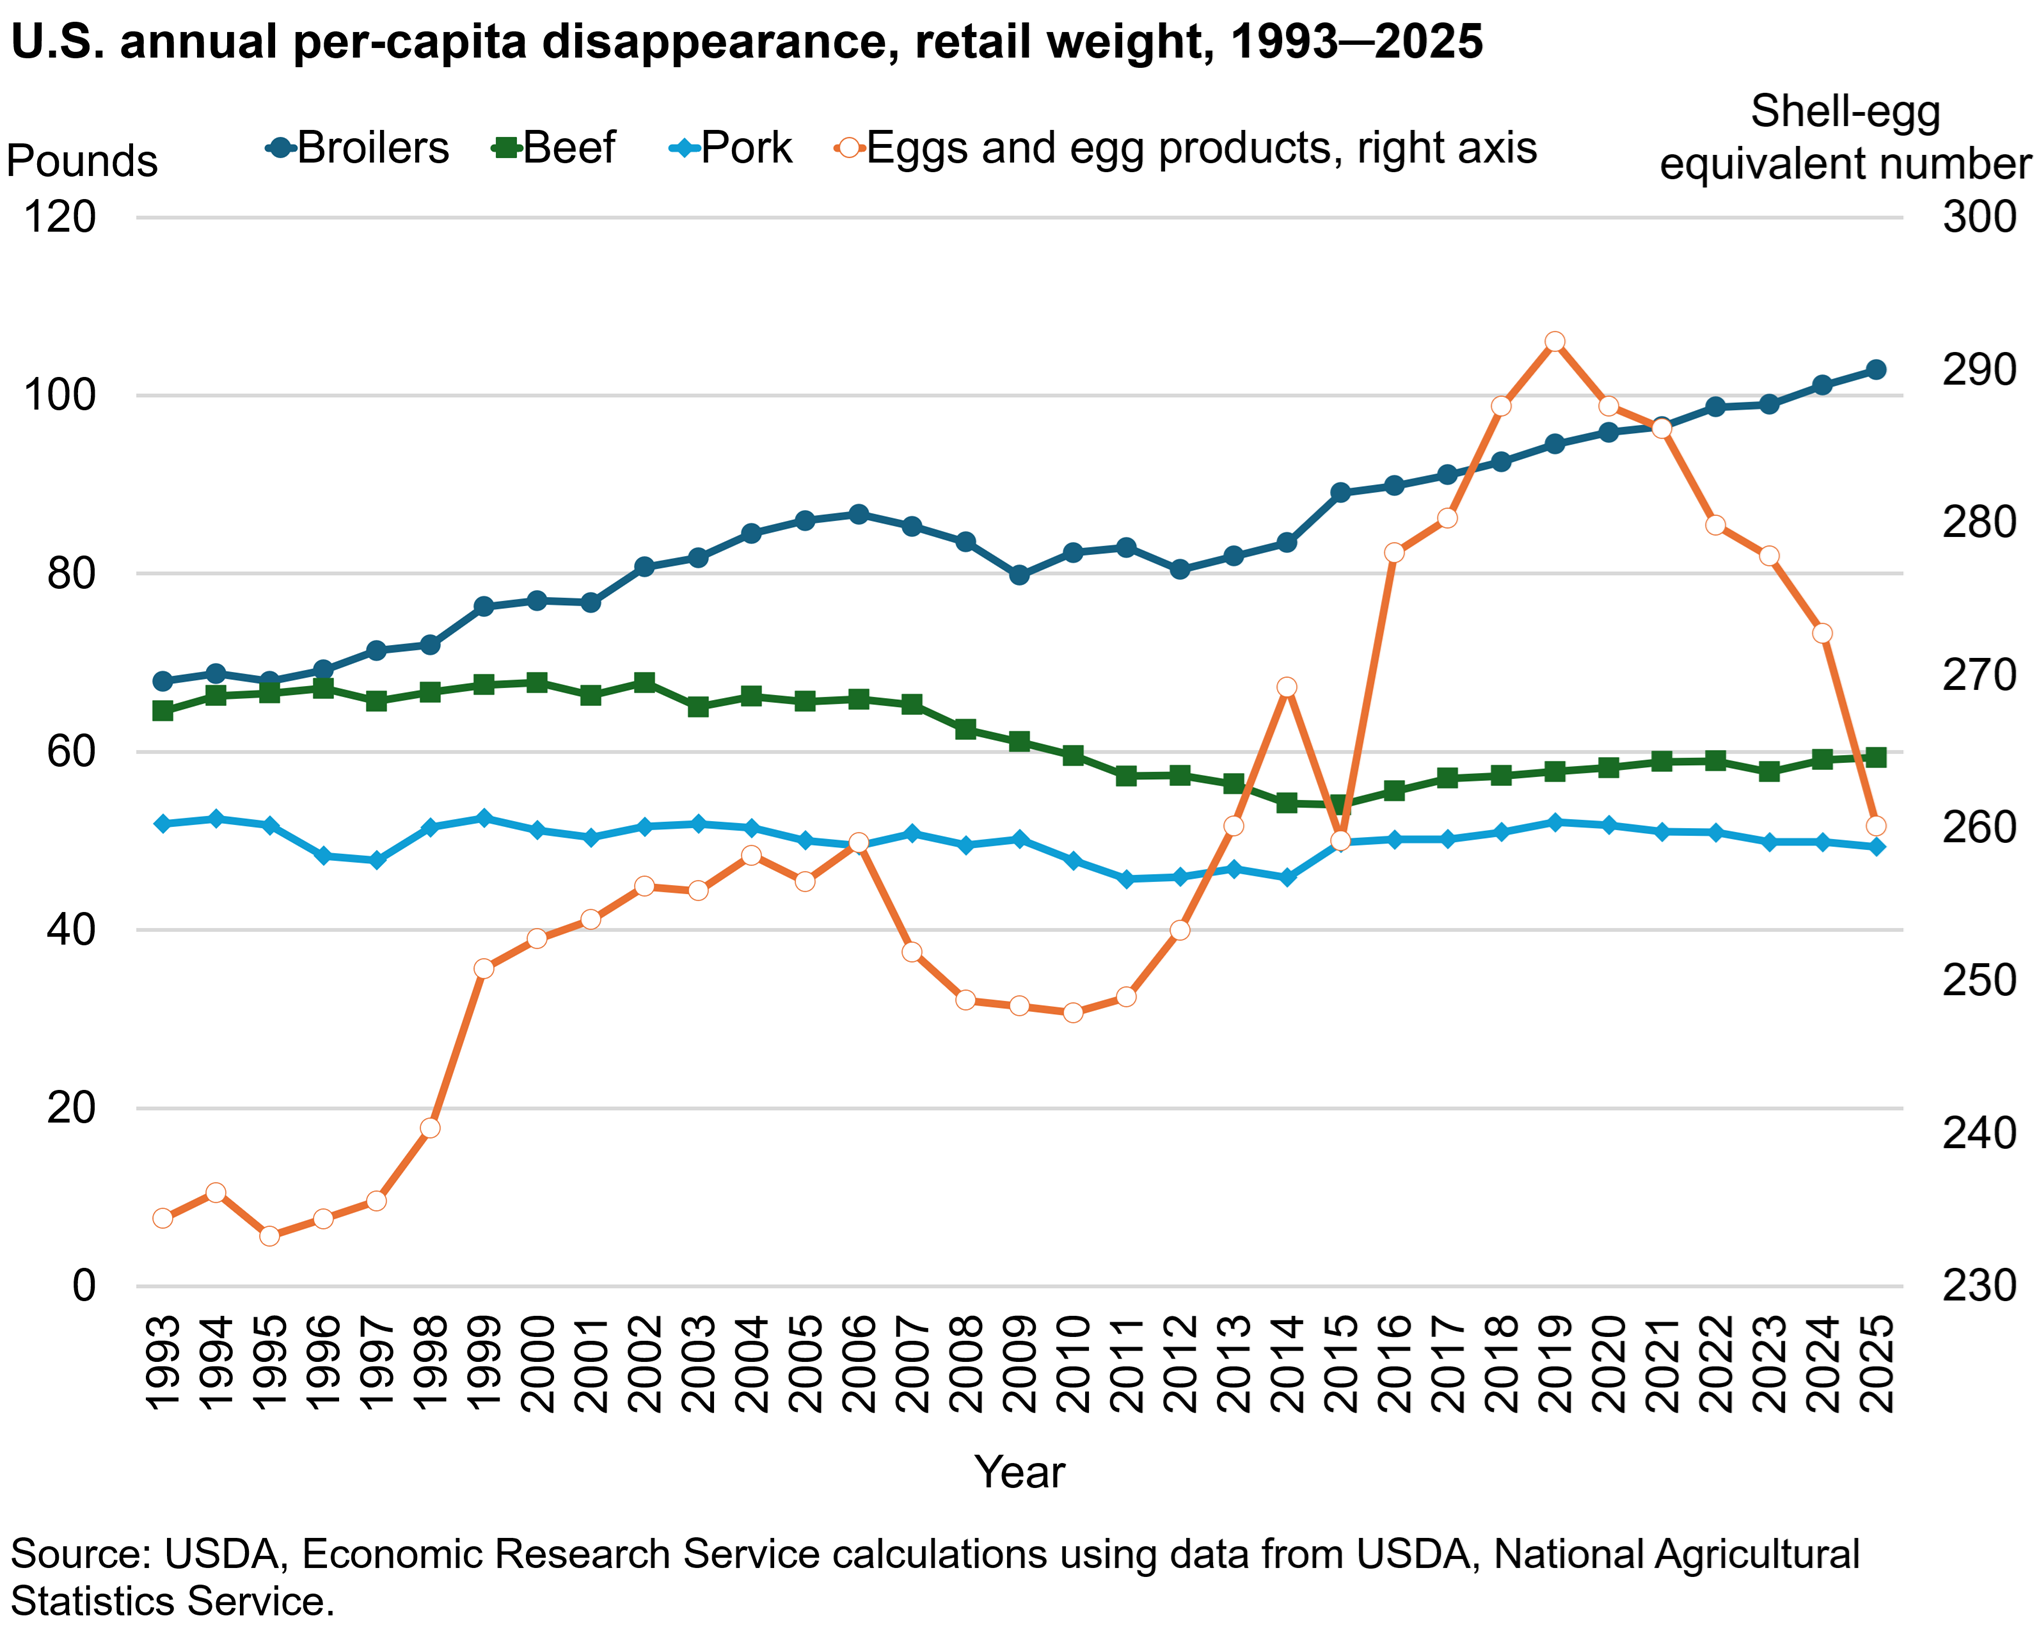
Download chart image | Chart data
Trade
Trade impacts the U.S. poultry sector’s profitability by altering domestic supplies and prices from what they would have been without foreign markets. In 2025, 13.9 percent of domestic broiler production was exported, making broilers the most export-oriented of the major U.S. poultry commodities. In 2025, 8.7 percent of domestic turkey-meat production was exported, and 2.3 percent of domestic egg production (including both hatching and table eggs) was exported.
The majority of U.S. broiler exports by weight are leg quarters and other products categorized as dark chicken meat, and Mexico is the most significant foreign market for broiler meat. Mexico is also the destination for most U.S. turkey exports, typically as cut-up parts shipped fresh or chilled for use for further processing. The largest markets for U.S. egg exports are Mexico and Canada.
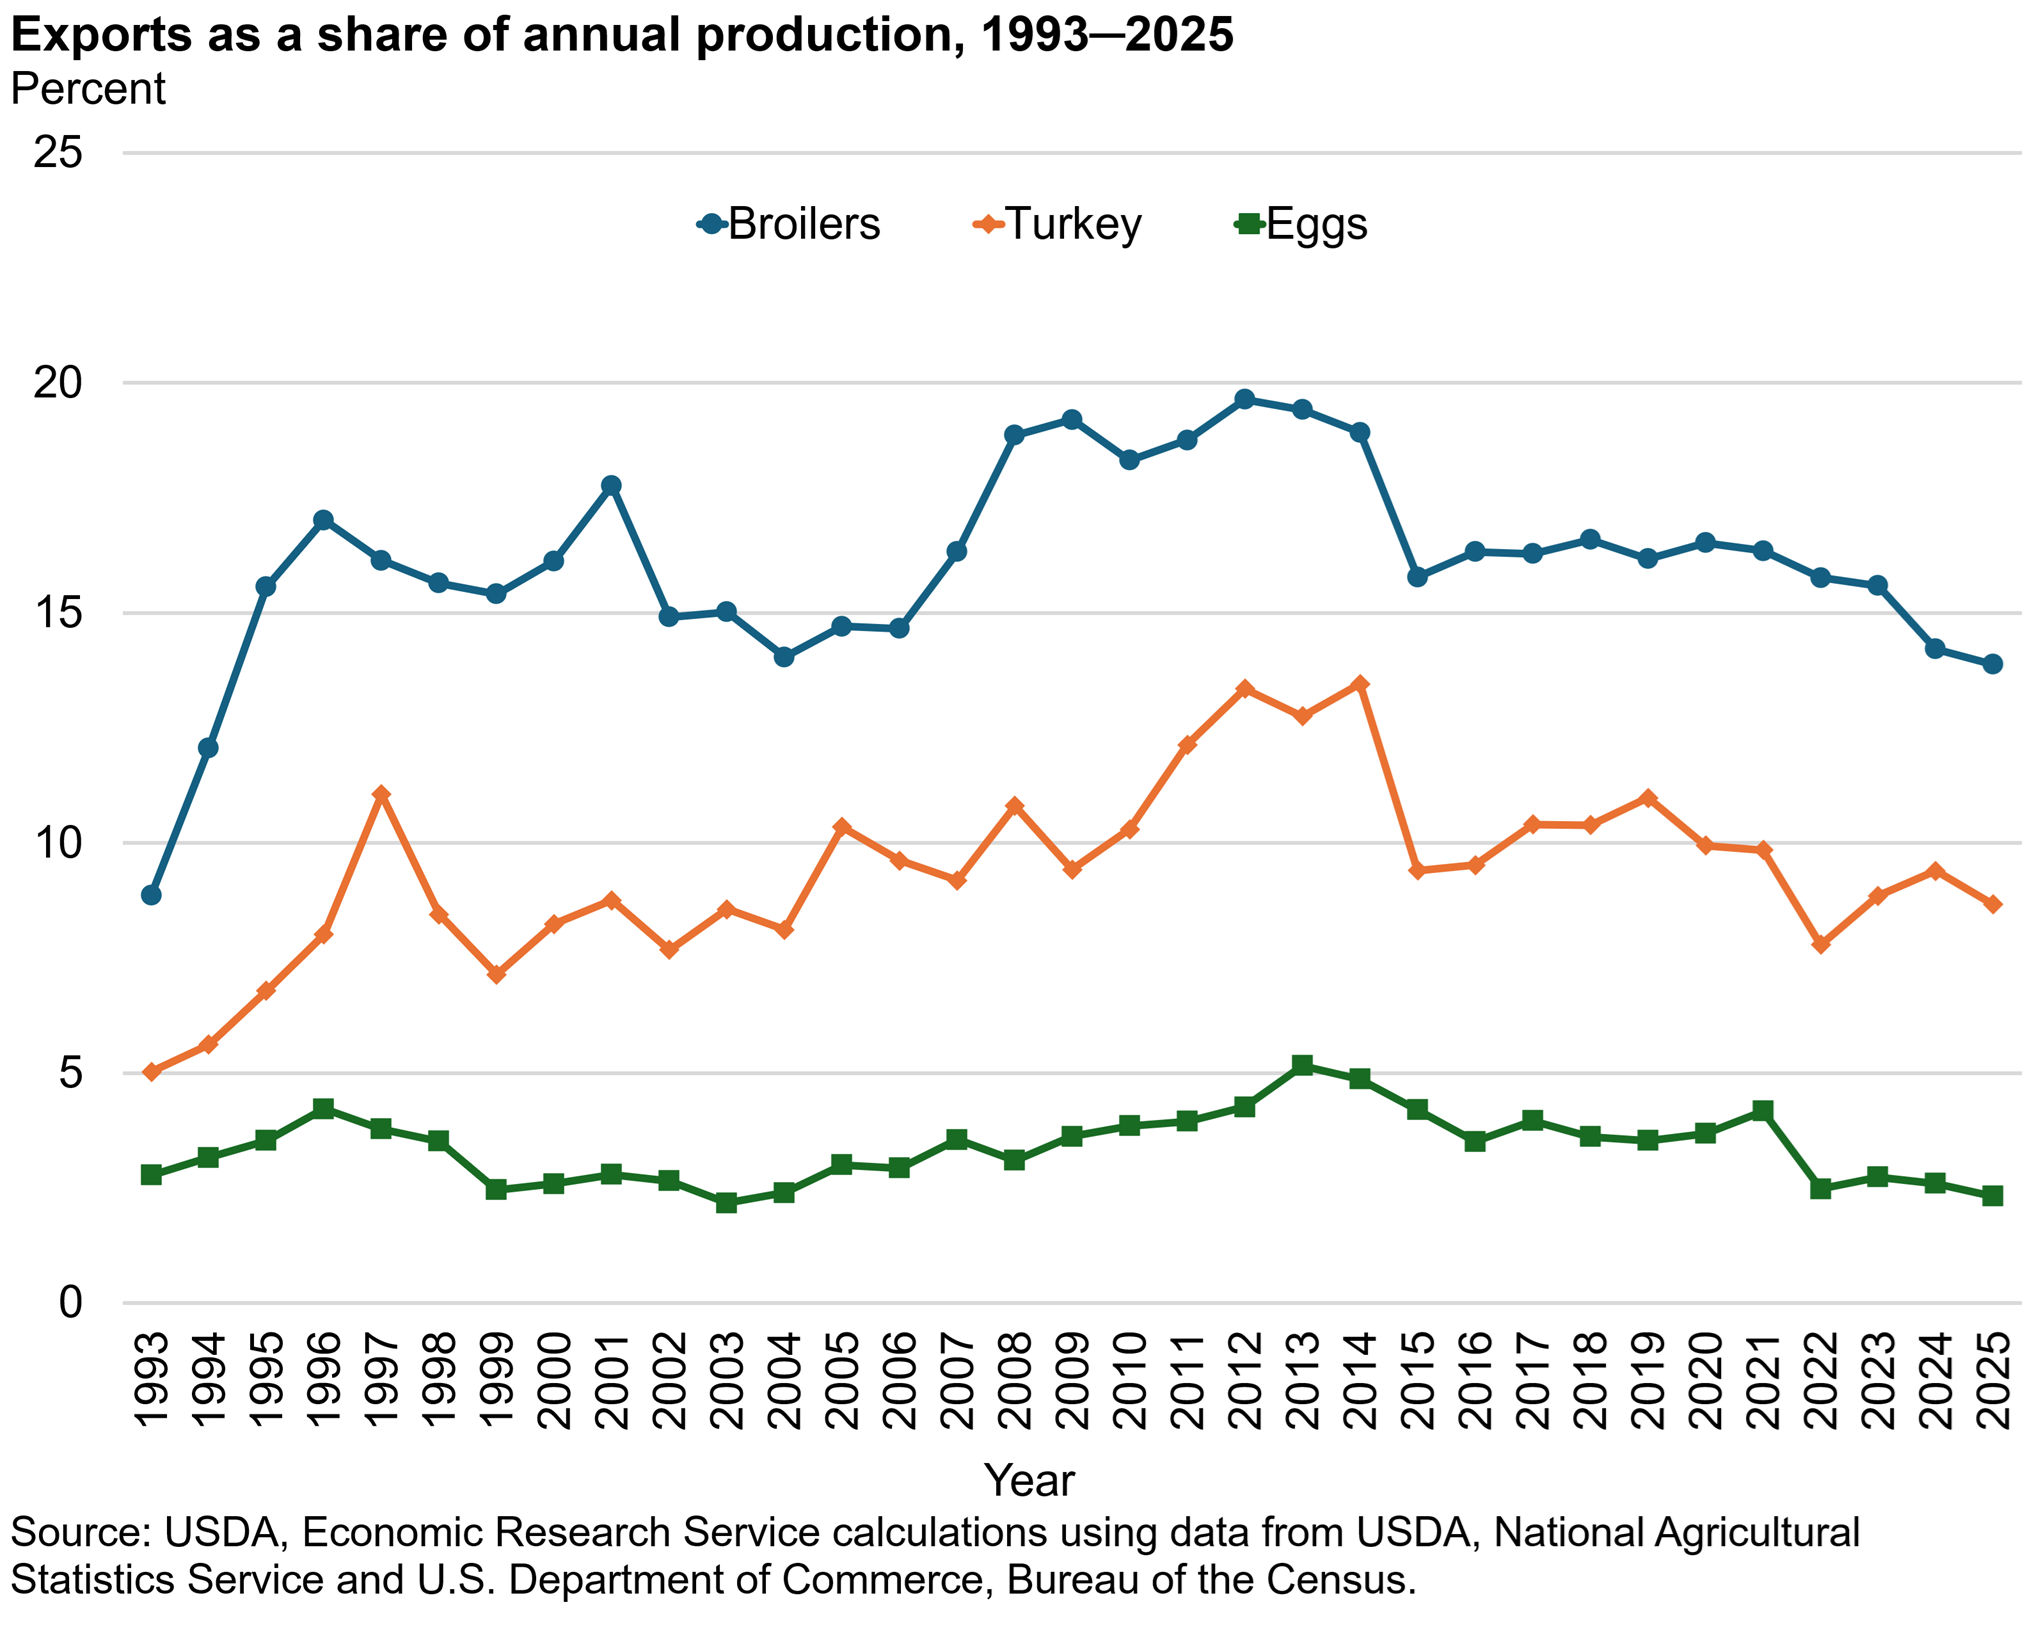
Download chart image | Chart data
For more summary statistics of the poultry sector, download Poultry Sector Summary Statistics.